RF Insights: September Market Update
Grayson Daniels, VP of Grain Merchandising and Procurement, shares a soybean and rice market update for September.
Rice Fundamental Highlights
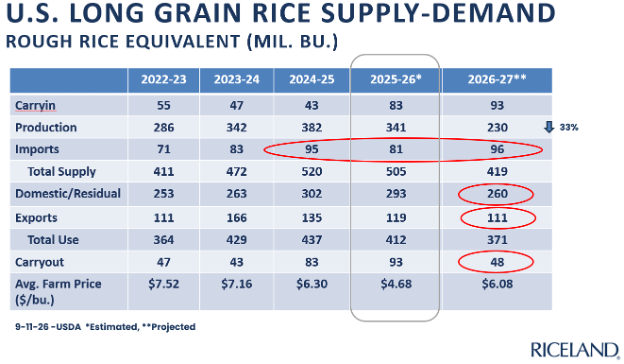
- The September WASDE report decreased old crop domestic use from 304 million bushels to 293 million bushels while adjusting exports up slightly, resulting in old crop ending stocks ballooning to 93 million bushels.
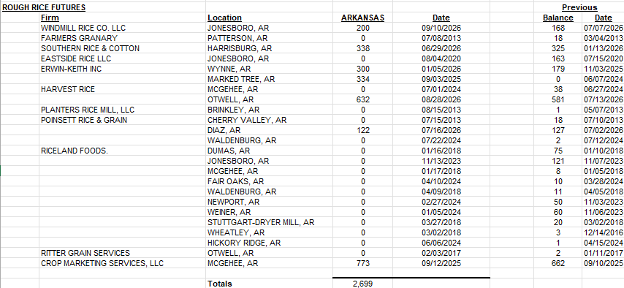
- CBOT certificates stand at 2699 after the September delivery cycle. Large old crop stocks, coupled with a CBOT milling yield premium and discount schedule that is not reflective of the current trade, are contributing to the record receipts and lack of cancellations.
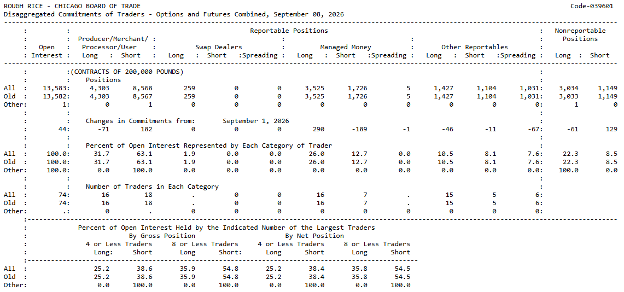
- CFTC Commitments of Traders show the fund segment, as well as the mid-level and small traders, continuing to grow their net long position; adding to their net long position 254 contracts from the prior week of reporting. The commercial segment is increasing their net short position with new crop farmer selling.
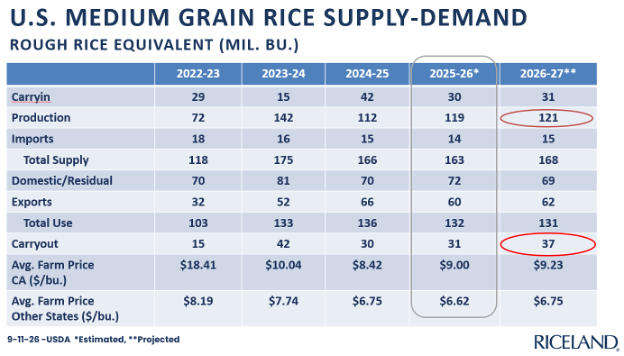
- The September 11 NASS Crop Production report cut the new crop U.S. long grain yield from 170 to 165 bushels per acre while increasing medium grain yields from 170 to 182 (including California).
- USDA’s September WASDE incorporated the updated yield estimates and harvested acres, resulting in a new long grain production estimate of 230 million bushels from the 2026 crop, a reduction of 33% from last year. Domestic use was left at 260 million bushels, however that number still looks unrealistically low.
- Projected imports for the new crop year were left at 96 million bushels, a record high if correct.
- The projected ending stocks for the 2026/27 crop increased to 48 million bushels.
- Milled rice prices continue to increase, but at a much slower pace than CBOT rough rice, thus prompting basis to be much weaker than normal. Milled rice prices should make stronger gains as the current large stocks get worked down.
- The extreme heat this year is driving milling yields much lower than standard, which will cause rough rice stocks used in domestic milling to get consumed even faster than expected.
Spot Rough Rice Futures
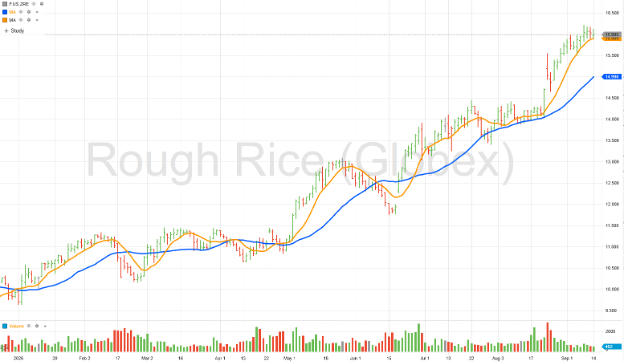
Orange Line = 9 day moving average
Blue Line = 27 day moving average
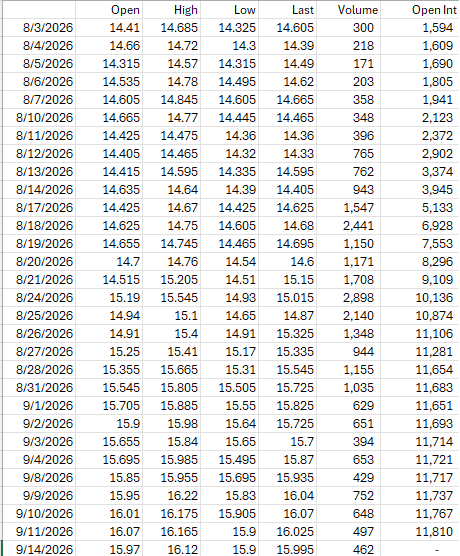
CBOT November ’26 Rough Rice Values, 8/3/26 through 9/14/26
U.S. Long Grain Rice Supply-Demand
CBOT Receipts As of 9-14-26
CFTC Commitments of Traders
U.S. Medium Grain Rice Supply-Demand
Soybean Fundamental Highlights
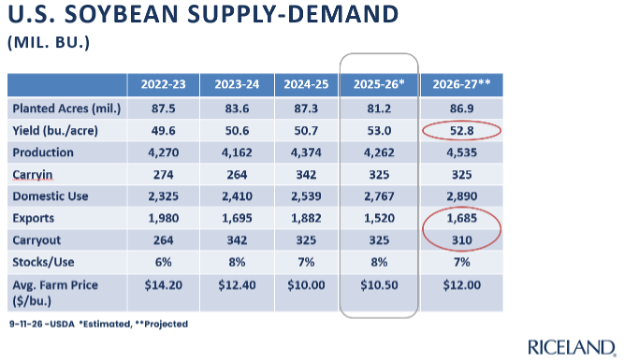
- The September 11 crop production report projected total U.S. soybean acres at 86.9 million, compared to 81.2 million last year.
- The September WASDE left old crop ending stocks at 325 million bushels.
- The soybean market has been influenced by Iran war developments, Chinese purchases and corn belt weather in recent weeks. Over the next few months harvest yield reports and Chinese purchases will be the key market factors.
- The September WASDE increased production and usage slightly, resulting in projected ending stocks decreasing from 320 million bushels to 310 million bushels.
November ‘26 Soybean Futures
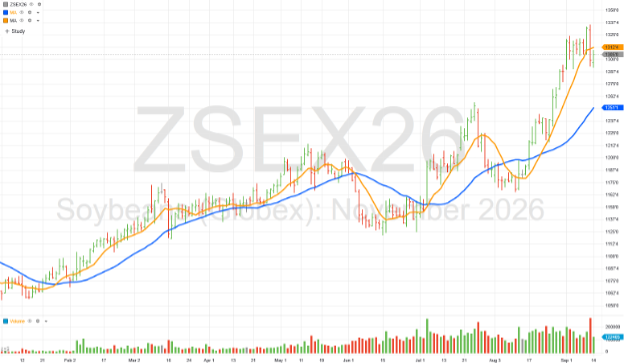
Orange Line = 9 day moving average
Blue Line = 27 day moving average
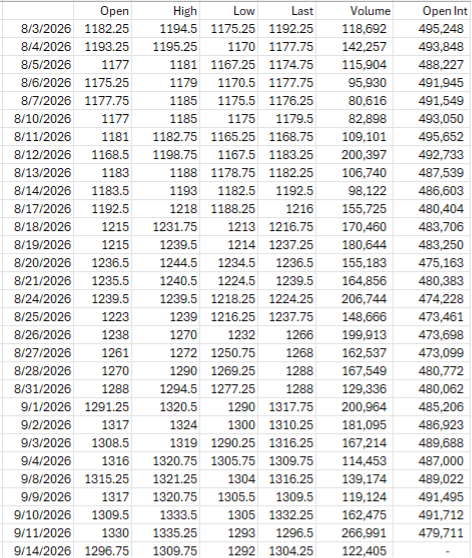
CBOT November ’26 Soybean Values, 8/3/26 through 9/14/26
U.S. Soybean Supply-Demand
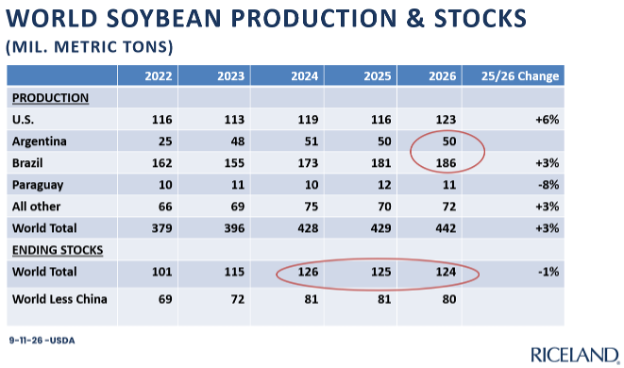
World Soybean Production & Stocks
River / Weather
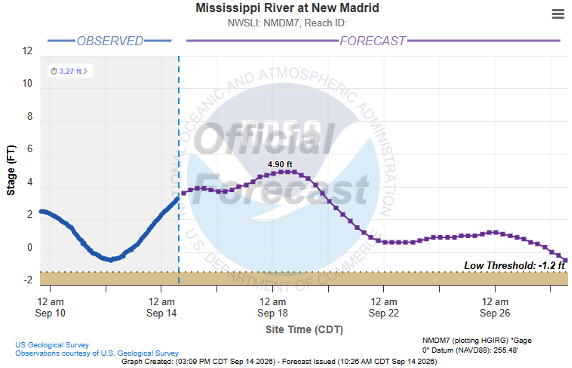
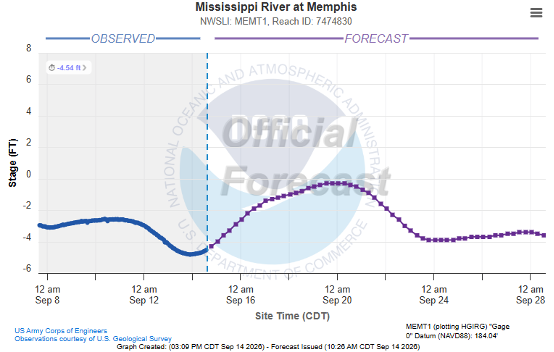
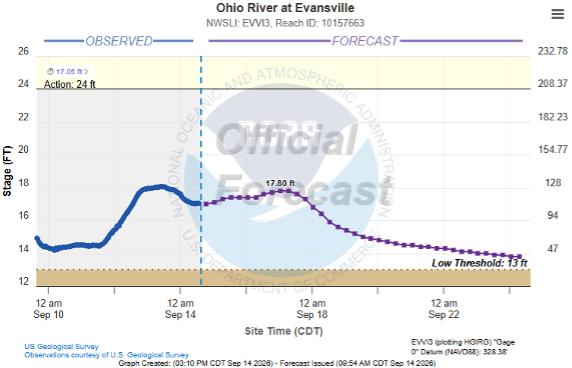
The Mississippi River graphs show a short-term rise before dropping later in the month. Forecasted heavy rains in the Midwest could prevent levels dropping as low as forecast. Ample water for navigation looks to be ensured for at least another 3 weeks. Additional rainfall will be needed to maintain adequate levels into October.
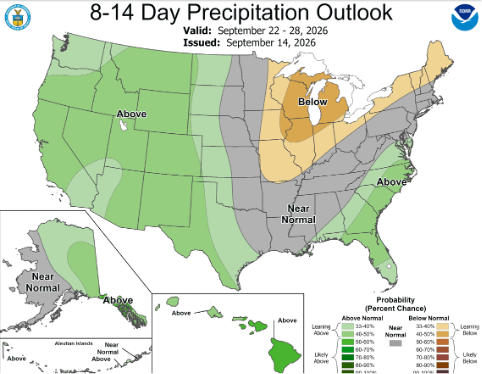
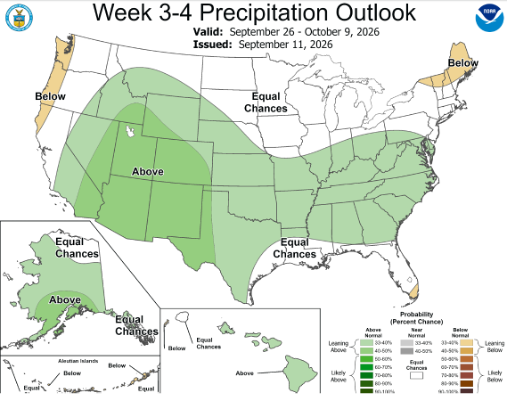
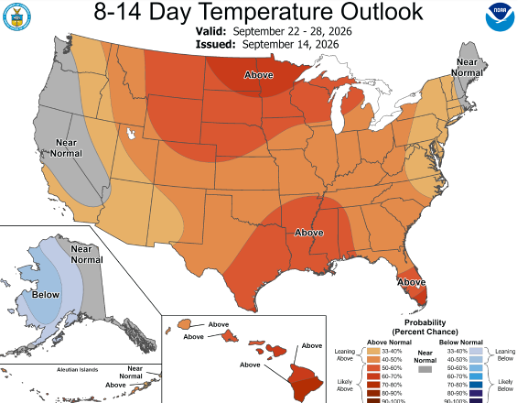
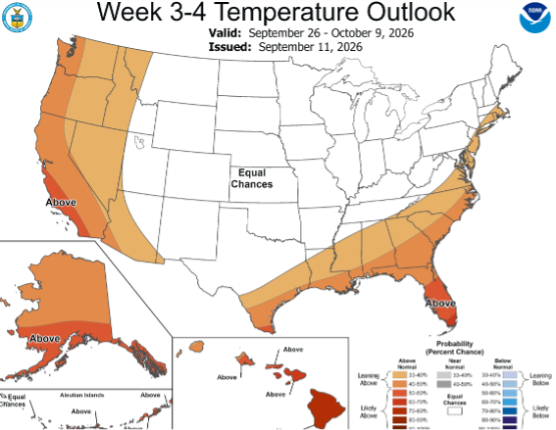
The near-term precipitation outlook shows potential for light rains in Arkansas and Southeast Missouri. The 3-4 week outlook is for slightly above normal chances of rain for the late September/early October timeframe. Temperatures are expected to remain above normal for the next few weeks.
NWS 7 day Precipitation Forecast
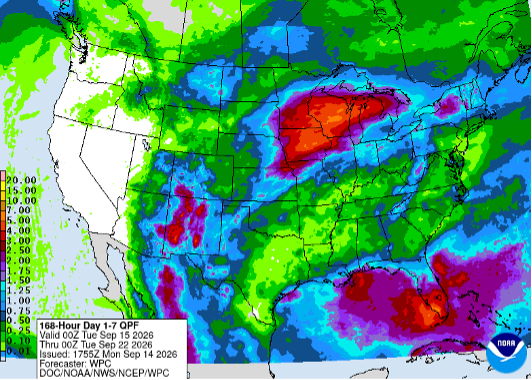
NOAA Precipitation and Temperature General Outlook